How the Student Loan calculator works
Monthly payment
M = B × r(1 + r)n ÷ ((1 + r)n − 1)
- B
- balance when repayment starts, including any capitalized interest
- r
- interest rate ÷ 12
- n
- number of monthly payments
Federal Tiered Standard term (loans made on or after July 1, 2026)
Under $25,000: 10 years; $25,000–$49,999: 15; $50,000–$99,999: 20; $100,000 or more: 25
Worked example
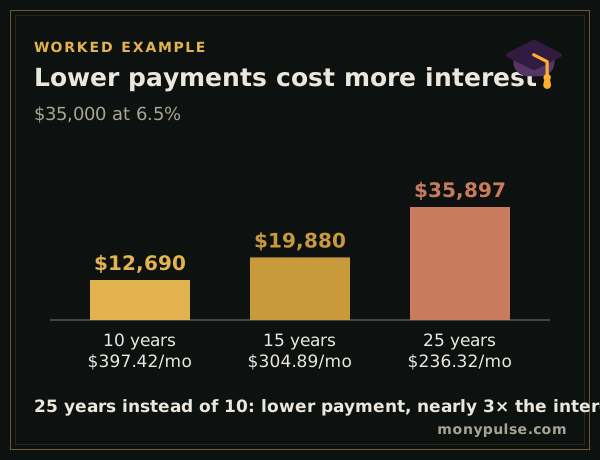
A $35,000 balance at 6.5% repaid over 10 years costs $397.42 a month and $12,690.15 in interest. Adding $100 a month cuts the interest to $9,186.19, saving $3,503.97, and you are debt-free 2 years, 7 months sooner.
If these were federal loans made on or after July 1, 2026, the Tiered Standard plan would set a 15-year term for this balance, with a payment of $304.89: lower each month, but more interest overall.
Federal repayment plans changed in 2026
The 2025 budget law reshaped federal student loan repayment. Starting July 1, 2026, borrowers can use two new plans: the Tiered Standard plan, with fixed payments over 10 to 25 years based on the amount owed, and the Repayment Assistance Plan (RAP), an income-driven plan. Borrowers with new loans made on or after that date choose between these two. Borrowers whose loans are all older keep some existing options during a transition that runs to July 1, 2028.
This calculator handles the fixed-payment side: a standard 10-year schedule, any custom term and the Tiered Standard term. For income-driven payments, use the official calculator on StudentAid.gov with your income and family size.
Paying student loans off faster
Extra payments cut interest because they reduce the balance that interest is charged on. To get the most from them:
- Tell your servicer to apply extra money to principal, starting with the highest-rate loan.
- Put windfalls such as tax refunds toward the loan; try the amount in the extra payment box.
- Keep paying while still in school if you can, so unsubsidized interest doesn’t get added to the balance.
Related calculators
If you have several loans plus a car loan or cards, the debt payoff calculator orders them by rate or balance. To find room in your budget for extra payments, use the budget calculator, and for any other fixed loan, the loan calculator.
Assumptions and limits
- One loan, or several loans entered as one balance at their balance-weighted average rate.
- A fixed rate and level monthly payments. Federal Direct Loan rates are fixed for the life of each loan.
- Income-driven plans, including the new Repayment Assistance Plan, set payments from income and are not modeled here.
- Extra payments go to principal. Ask your servicer to apply them that way rather than to future payments.
Frequently asked questions
How are student loan payments calculated?
On a standard plan, the balance is spread over the term in equal monthly payments using the amortization formula, so each payment covers that month's interest and pays down part of the balance.
What is the federal Tiered Standard plan?
It is the fixed-payment plan for federal student loans made on or after July 1, 2026. The term is 10, 15, 20 or 25 years depending on how much you owe, so larger balances get longer terms and lower payments.
Is there a penalty for paying off student loans early?
No. Federal law bars prepayment penalties on federal and private student loans, so any extra amount goes toward the balance and cuts future interest.
Should I pay extra on student loans or invest?
Each extra dollar saves interest at the loan's rate, a known return, while investment returns vary and can be negative. A common rule of thumb is to get any employer 401(k) match first, then compare the loan's rate with the return you expect after tax. That is a general guideline, not advice for your situation, and federal loans have repayment plans and forgiveness programs that can change the math.
How do I combine several loans?
Add the balances and use the balance-weighted average rate. To target the highest-rate loan first instead, list each loan in the debt payoff calculator.
Sources and method
- Fact Sheet: The Trump Administration Is Simplifying Student Loan Repayment · U.S. Department of Education
- Repayment plans · Federal Student Aid, U.S. Department of Education
- Federal interest rates and fees · Federal Student Aid, U.S. Department of Education
Formulas and figures checked against these sources on November 12, 2026. The calculator runs entirely in your browser; nothing you type is sent to us or stored. Results are estimates for education, not financial, tax or legal advice, and MonyPulse is not a lender, tax preparer or investment adviser. Found an error? Tell us. See how we build and test our calculators and our editorial standards.