How the Amortization calculator works
Scheduled payment
M = P × r(1 + r)n ÷ ((1 + r)n − 1)
- P
- loan amount
- r
- monthly rate: the annual rate ÷ 12
- n
- number of payments: years × 12
Each row of the schedule
Interest = Balance × r; Principal = M − Interest + Extra; New balance = Balance − Principal
Worked example
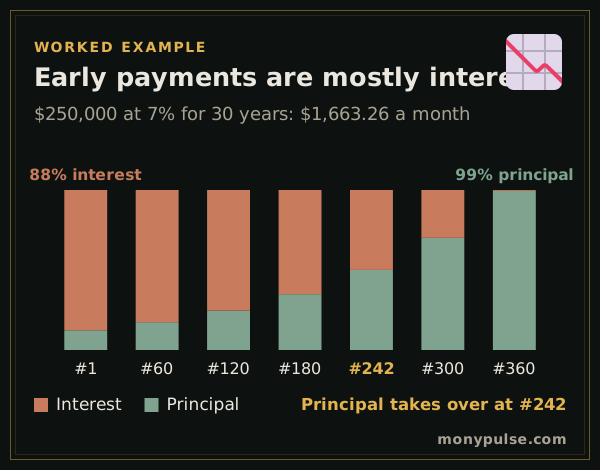
Take a $250,000 loan at 7% for 30 years. The monthly payment for principal and interest is $1,663.26. Of the very first payment, $1,458.33 is interest and only $204.92 reduces the balance.
That split slowly reverses. Principal finally becomes the larger part of the payment at payment number 242, and over the full 30 years the loan costs $348,772 in interest. The line chart shows the balance falling slowly at first and faster near the end.
How to read the schedule
Each row is one payment. Interest is the month’s charge on the balance you owed going in. Principal is the rest of the payment, plus any extra you added. Balance is what you still owe afterward, which is also roughly what it would take to pay the loan off that month. The first 24 rows are shown; select Show all for the rest, or download the full table.
How extra payments change the schedule
You can test three kinds of extra payment, alone or together:
- Monthly extra: a fixed amount added to every payment.
- Yearly extra: for example a tax refund or bonus put toward the loan every twelfth payment.
- One-time payment: a single lump sum with the payment number you choose.
The results show the interest saved and how much sooner the loan ends. Before sending extra money, ask your lender to apply it to principal and check the loan for a prepayment penalty. Most mortgages made today have none, but some loans charge one in the first few years.
Related calculators
For a home loan with property tax, insurance and PMI in the payment, use the mortgage calculator. For a quick payment and payoff date on any loan, use the loan calculator, and to weigh a new rate against your current one, try the refinance calculator.
Assumptions and limits
- A fixed rate and a fixed monthly payment for the whole loan.
- Extra payments go entirely to principal in the month they are made and do not change the required payment.
- The schedule shows principal and interest only. Escrow for tax and insurance, PMI and late fees are not included.
- Cents are kept in the math and rounded only for display, so the last payment can differ from the others by a few cents.
Frequently asked questions
What is an amortization schedule?
It is a table of every payment on a loan showing how much goes to interest, how much goes to principal and the balance left afterward. Lenders use the same math, so the schedule lets you see your balance on any future date.
Why does principal grow with each payment?
Interest is charged on the remaining balance. Each payment lowers the balance a little, so the next month's interest is a little smaller and more of the same fixed payment is left for principal.
Is it better to pay extra every month or once a year?
The earlier extra money arrives, the more interest it saves, so $100 a month saves a bit more than $1,200 paid at the end of each year. Both shorten the loan. Enter either one under Extra payments to compare.
Can I download the schedule?
Yes. Use the Download CSV button under the table to get every payment with the exact figures, which opens in Excel, Google Sheets or Numbers.
Does an extra payment lower my monthly payment?
Not on a standard loan. The payment stays the same and the loan ends sooner. Some mortgage lenders will re-amortize, or recast, the loan after a large lump sum for a fee, which does lower the payment.
Sources and method
- What is amortization and how could it affect my auto loan? · Consumer Financial Protection Bureau
- What is a prepayment penalty? · Consumer Financial Protection Bureau
- What is the difference between a mortgage interest rate and an APR? · Consumer Financial Protection Bureau
Formulas and figures checked against these sources on November 11, 2026. The calculator runs entirely in your browser; nothing you type is sent to us or stored. Results are estimates for education, not financial, tax or legal advice, and MonyPulse is not a lender, tax preparer or investment adviser. Found an error? Tell us. See how we build and test our calculators and our editorial standards.